Financial and consumer centre
São Paulo
The market a Brazilian company has to win, and the tax and traffic system it has to win inside.
BRICS
A large Portuguese-speaking domestic market with a startup statute, a heavy tax state, and a financial centre that is the city of São Paulo rather than the country.
Startup EcosystemsBrazil
Brazil’s federal answer to the startup question is Complementary Law 182 of 1 June 2021, the Marco Legal das Startups, published in the official gazette the next day. It sets a legal frame for innovative entrepreneurship, amends the corporations law and the small-business statute, and deals with subjects that include public contracting, regulatory sandboxes, and the angel investor. Parts of the original bill were vetoed. The Câmara record is the place to see what is actually in force. Thresholds in the statute are not copied onto this page.
The statute did not abolish the federative tax system. Federal, state, and municipal taxes still meet inside a single invoice. Consumption-tax reform has been passed as a constitutional change and will take years to become the system people actually file. Until a company is inside the new system, the old complexity is the operating environment, not a footnote.
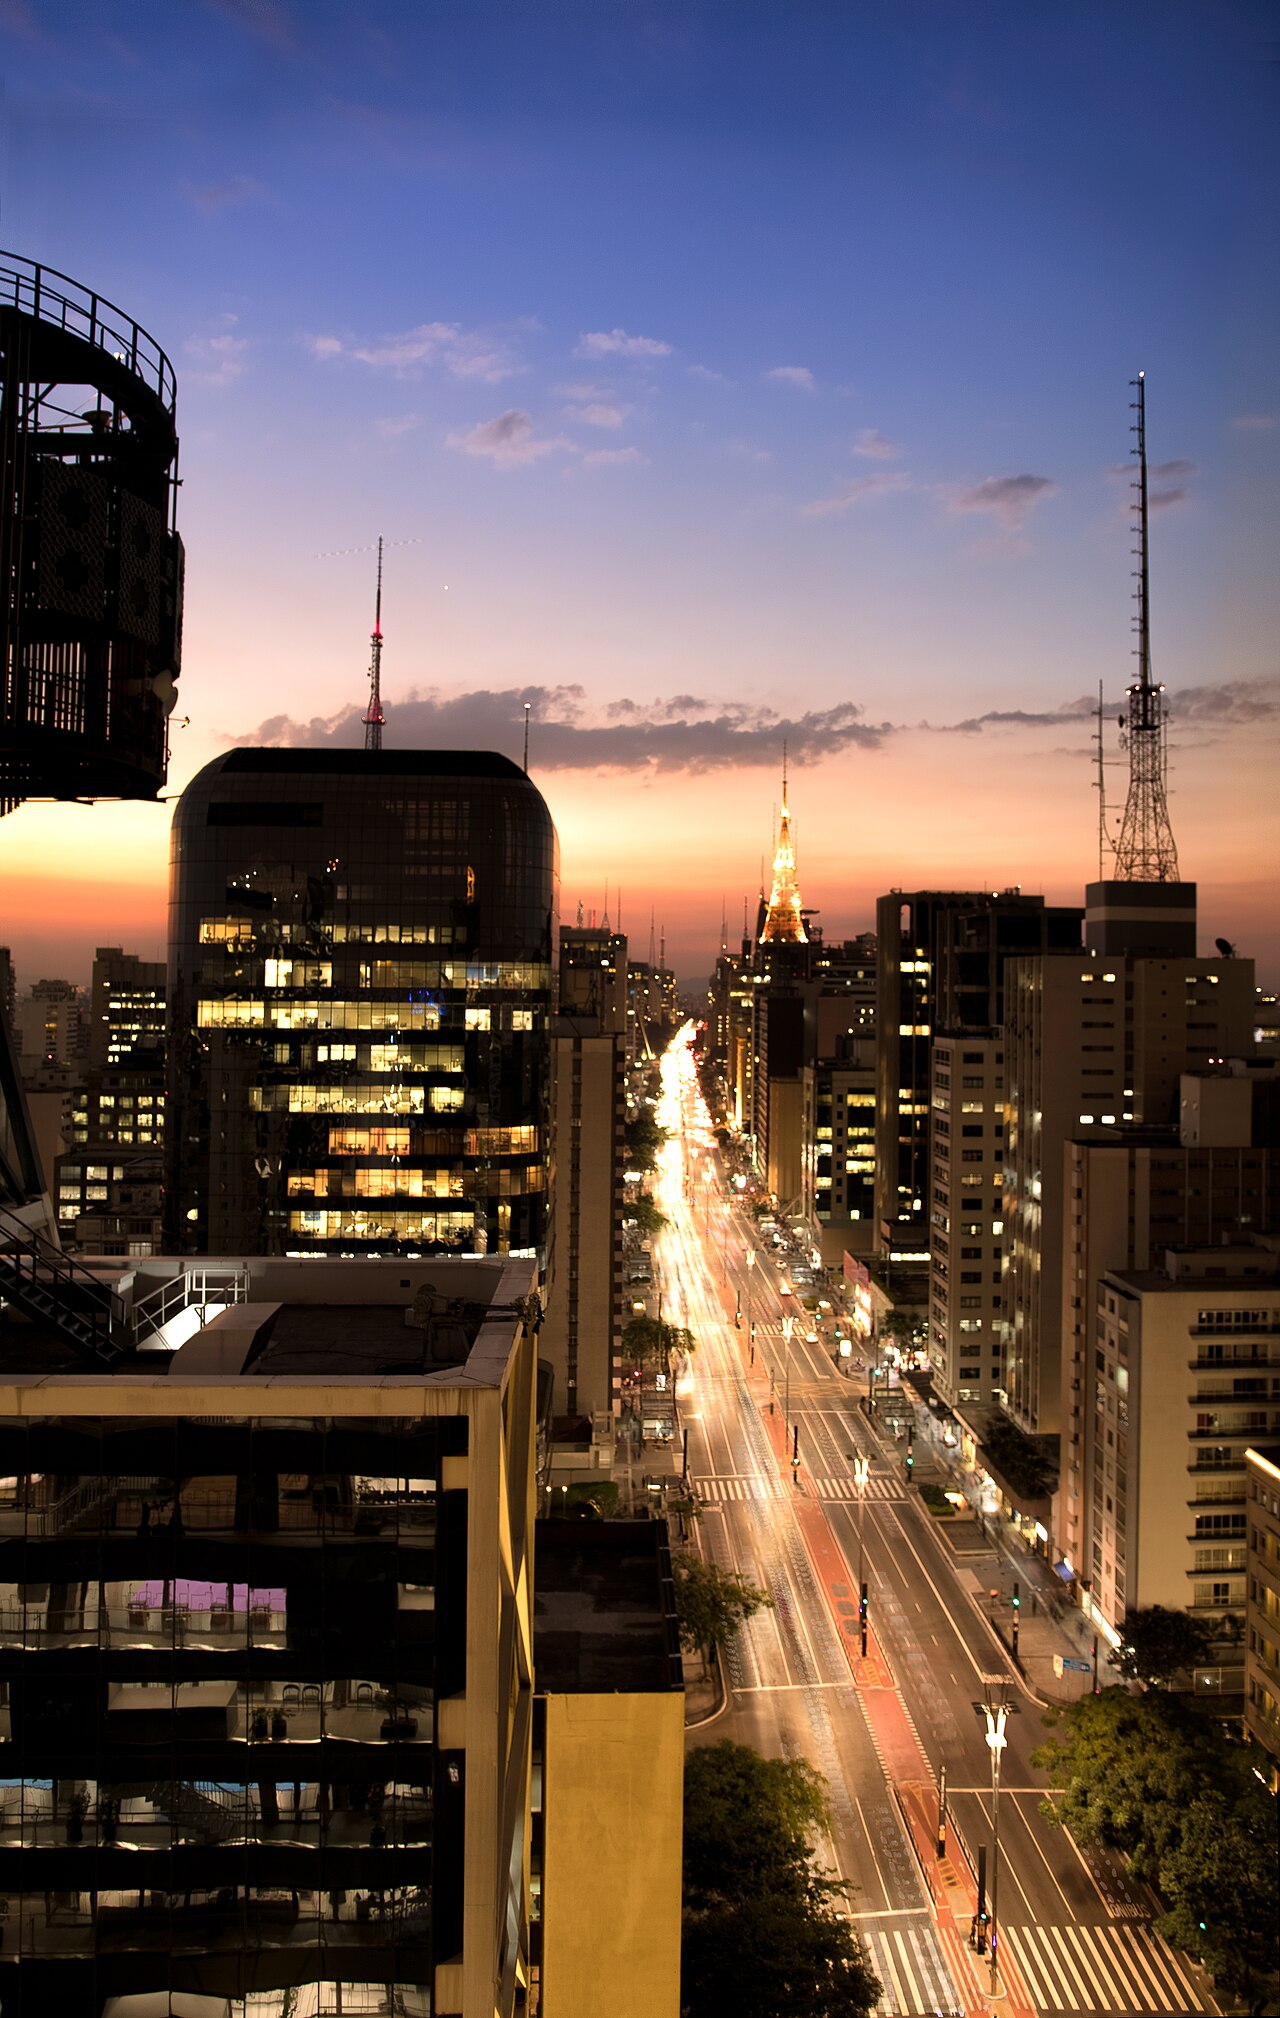
São Paulo is the commercial and financial centre and is not the federation. Other cities have universities, public-research money, and real firms. They do not have the same customer density. The city brief below is deliberately one city, not a tour.
Separate urban systems, in the order they are discussed.
The same ten questions for every major cluster. Answers are qualitative. They are not scores, and they do not rank countries against each other.
São Paulo is the commercial and financial centre and the only city briefed. Campinas, in the same state, has research institutions and is not São Paulo. Other capitals have firms and universities. They are not given a page until the customer is different from São Paulo’s.
The thick sectors are software and payments around a domestic service economy, consumer distribution, and a narrower scientific layer tied to public research. Agriculture is a national industrial system of its own and should not be folded into a startup adjective without a specific company type.
Local funds, corporate investors, and public development institutions such as BNDES and FINEP all exist and are not substitutes. The 2021 startup law created a statutory language for angel investment. It did not make angels the source of scale-up capital. Foreign funds add exchange registration and tax.
Portuguese is the customer language. Banks and large IT departments train the workforce and compete for it. The University of São Paulo and Unicamp, the latter in Campinas, are research institutions, not a hiring plan.
Complementary Law 182 of 2021 is the federal startup statute, with vetoes recorded by the Chamber of Deputies. Tax remains federal, state, and municipal. Payments meet the Central Bank. A sandbox is a supervised exception.
The domestic market is the reason to accept the tax and labour complexity: a large Portuguese-speaking economy. No GDP figure is printed. Mercosur is not a single market a software company can treat as home. Spanish-speaking neighbours are a second launch.
São Paulo is the international air gateway and the place foreign firms put a Brazil headquarters. That is managerial connectivity. Physical export goes through a coastal port system that most software companies never see and every goods company must.
Domestic aviation connects the major cities. Roads, urban time inside São Paulo, and freight across a continental country are the constraints on anything that is not pure software.
Tax compliance, the cost of formal employment, and late payment by large customers stop more companies than a shortage of ideas. Consumption-tax reform is constitutional and unfinished as a filing system. Until it is the system people use, the old complexity is the environment.
A large home market in one language, with a real financial centre, can support companies that never become global. That is the potential. It is capped, for a given firm, by the cost of being formal. Which sector comes out ahead is not something this note will call.
High-growth firms sit on top of a huge population of small companies in a tax regime built for them. Most of those small companies are not startups. The 2021 law tries to mark the difference. Daily life still marks it by whether anyone outside the family has put in risk capital.
The sociedade limitada is the ordinary private company. A sociedade anônima is the corporations-law vehicle the startup statute touched. Choice of vehicle is a lawyer’s work because liability, investment instruments, and tax do not line up in one form. GRIP will not pick the form.
Local venture funds, corporate investors, and development institutions (BNDES and FINEP among the public ones) all exist. They are not substitutes. Foreign funds add an exchange registration and a tax question. The angel-investor provisions in the 2021 law are a statutory category, not evidence that angels are the main source of scale-up capital.
The strongest technical base in the startup system is software for a domestic service economy: finance, retail, logistics, health administration. Deep hardware is narrower and more tied to public research institutions than to the Paulista avenue office market.
Portuguese is the operating language. English is an overlay for fundraising and for some engineering teams, not for customers. Senior product and security talent is scarce relative to graduate volume. Services and bank technology departments are the training ground and the competing employer.
The University of São Paulo is the main research university people mean when they point at the city. Unicamp is in Campinas, in the same state and not in the same city. Federal universities elsewhere, and public research institutes, matter for science-based firms. A campus tour is not a map of customers.
The startup law sits beside the Central Bank for anything that touches payments, the securities regulator for anything that looks like a public offer, and the tax authorities at three levels. A sandbox, where a regulator offers one, is a supervised exception. It is not a general permission to launch.
The cost that does not show in rent is tax compliance and the price of employment. Labour charges and litigation risk are part of why companies stay small on the formal books. Doing Business ranks are not used. They were discontinued, and Brazil was one of the countries the method was bad at describing even before that.
Domestic aviation connects the major cities. Urban transport inside São Paulo is a constraint on where staff will work. Logistics across a continental country, with uneven roads and a serious port system on the coast, is the physical problem for any company that is not pure software.
The domestic market is the point: a large, unequal, Portuguese-speaking consumer and enterprise economy. Mercosur is a trade arrangement, not a single market a startup can treat as home. Selling in Spanish-speaking neighbours is a second company problem, not a feature of São Paulo.
Innovation that clears the market is often a way of distributing a service Brazil’s incumbents did badly: payments, retail logistics, credit to a customer the bank would not underwrite. Scientific innovation exists and has a longer path through public funding and regulation. Both are real. They belong in separate notes.
Scale means surviving formal employment, tax, and a customer who pays late, long enough to matter outside one city. The public market is B3, in São Paulo. Listing is rare relative to the number of companies that call themselves startups. A cross-border exit has to pass Brazilian exchange and tax rules on the way out.
Across GRIP
The same place, read from another desk.
Continue with GRIP
Country briefs are the law and the national system. City briefs are where hiring, customers and rent actually happen.