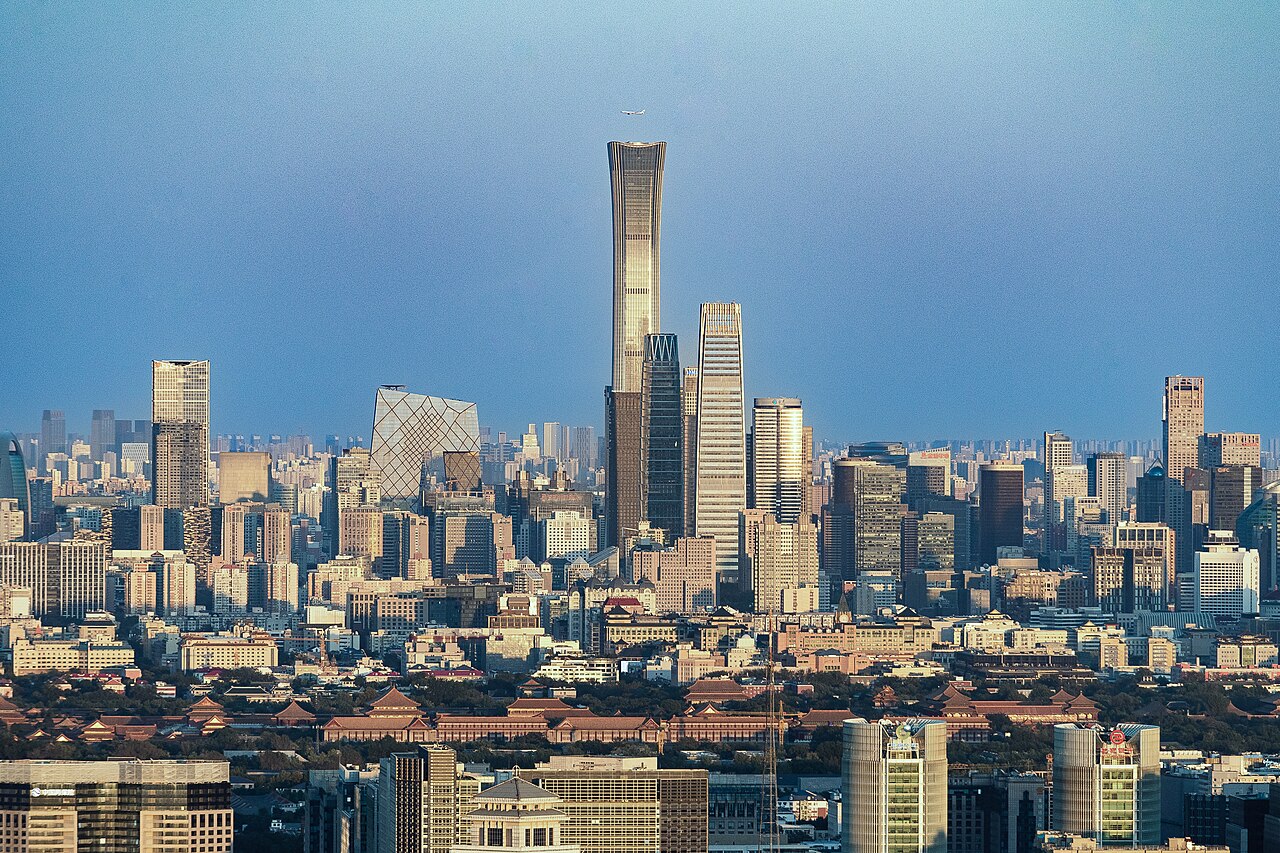
Rules, universities, headquarters
Beijing
The political and research capital. Regulatory risk is local because the rules are written here.
BRICS
A domestic market large enough to scale a company that never leaves, under a foreign-investment law built around a negative list and a data regime that now travels with the product.
Startup EcosystemsChina
China’s startup system is a domestic commercial system that foreign capital enters under a specific statute. The Foreign Investment Law, adopted in March 2019 and in force from January 2020, states pre-establishment national treatment plus a negative list. Sectors off the list are not supposed to need a prior approval merely because the investor is foreign. Sectors on the list are restricted or prohibited. The list is revised. This page does not copy it.
That law replaced an older patchwork of foreign-invested enterprise statutes. It did not replace sector regulators, the Communist Party’s role inside companies, cybersecurity rules, or capital controls. A company can be lawful to invest in and still be unable to move data or dividends the way a founder from another country expects.
The three cities below are not substitutes. Beijing is where universities, ministries, and the platform companies’ political risk sit. Shenzhen is a special economic zone tied to manufacturing in the Pearl River Delta. Shanghai is the commercial and multinational city, with Pudong’s financial and science parks. A national ‘China tech’ paragraph that ignores the split is not usable.
Separate urban systems, in the order they are discussed.
Rules, universities, headquarters
The political and research capital. Regulatory risk is local because the rules are written here.
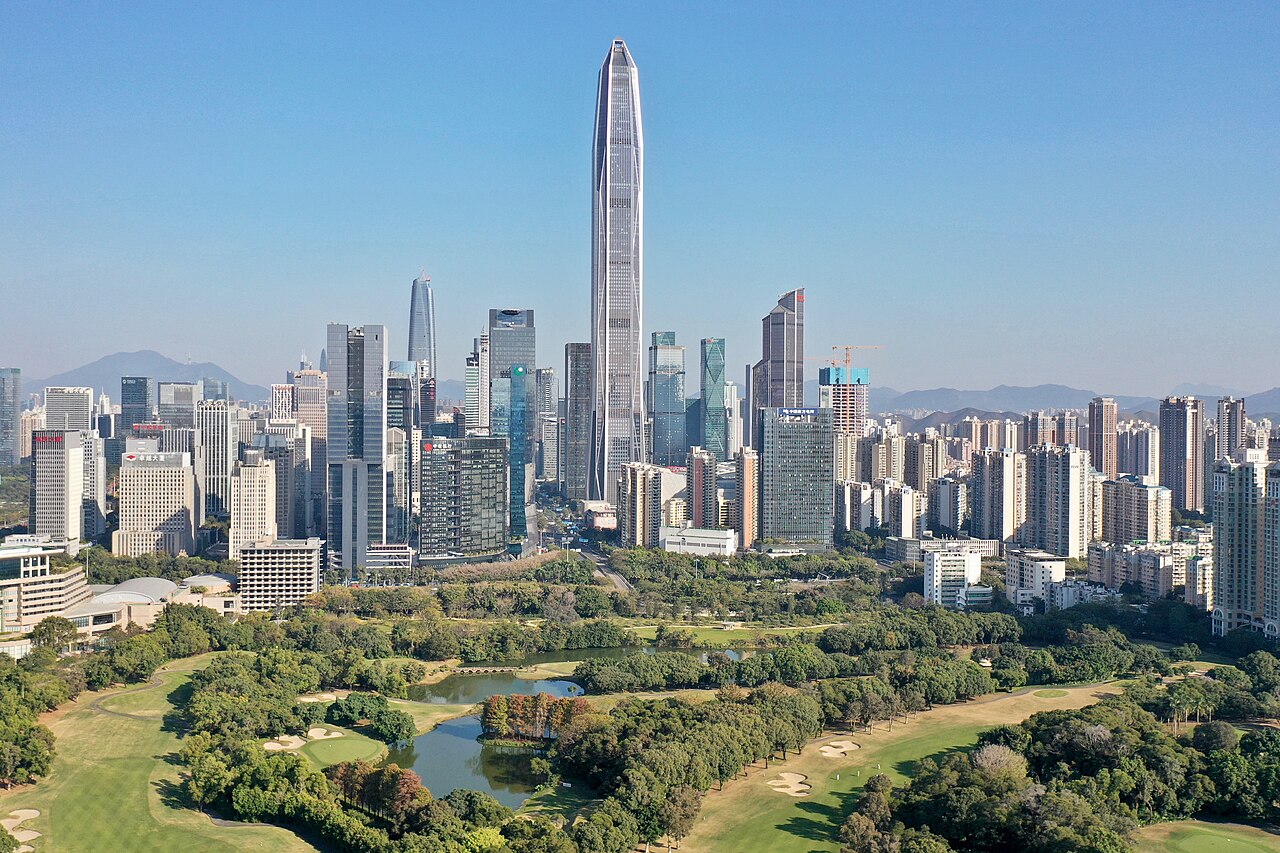
Hardware and the Pearl River Delta
A special economic zone whose advantage is the supplier base next door, not a campus brand.
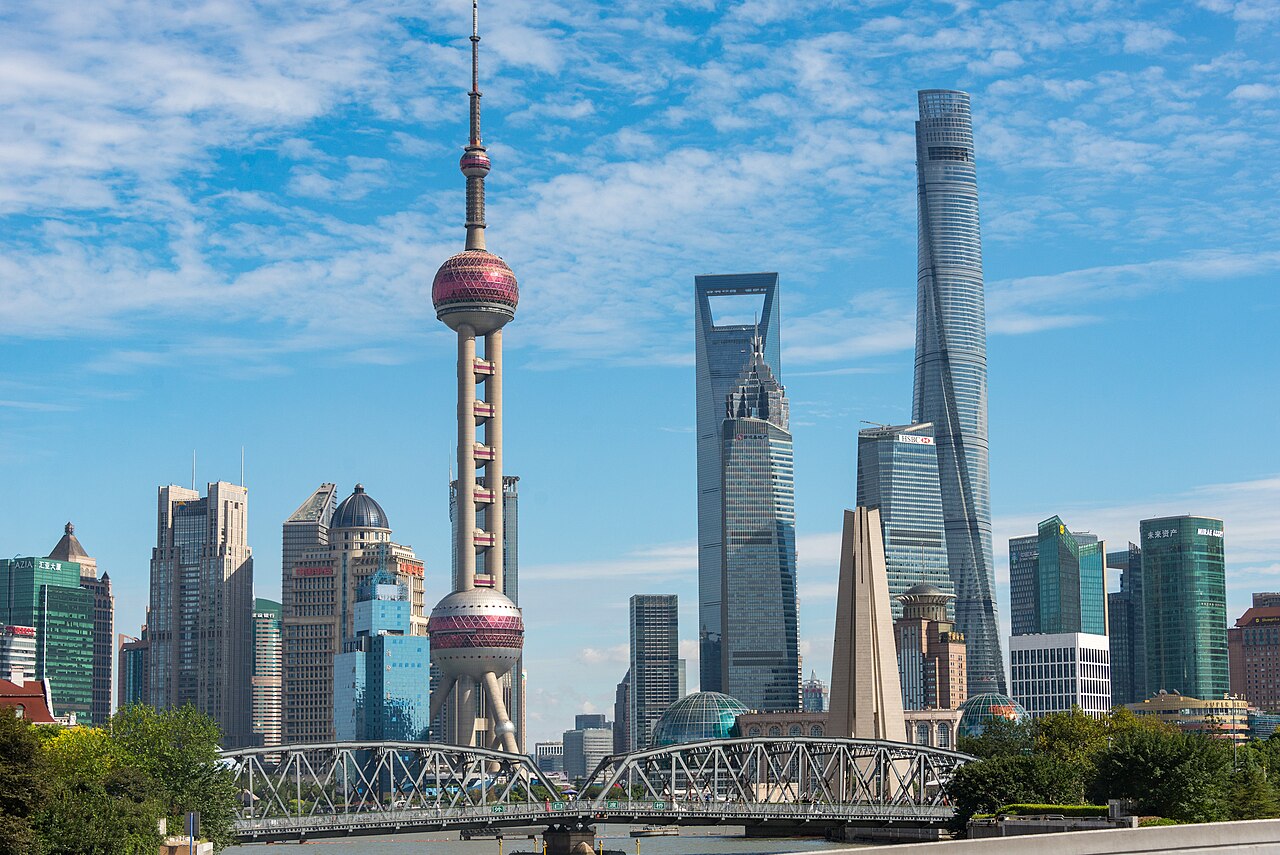
Commercial capital
Multinationals, Pudong, and a science park that is not the Bund.
The same ten questions for every major cluster. Answers are qualitative. They are not scores, and they do not rank countries against each other.
Beijing, Shenzhen, and Shanghai are briefed because they are different systems: rules and research, hardware and suppliers, and commercial headquarters. Hangzhou and other cities have real firms. They are not given a thin page here. Adding one requires a distinct customer or a distinct factory system, not a logo.
The sectors that are actually thick are manufacturing and hardware, enterprise and industrial software, and consumer platforms that live under content and data rules. A ‘leading sector’ claim in a foreign newsletter is not adopted. Presence is the test, and the city briefs say where.
Domestic venture, corporate money, and local-government guidance funds are available inside the system. Foreign money meets the negative list under the Foreign Investment Law and the investor’s own outbound rules. Availability is not the same as permission to exit.
Graduate supply from the major universities is deep. Housing policy and city registration still shape who stays. The competing employer is a large platform or a state-linked industrial firm, not only another startup.
The Foreign Investment Law is the cross-border statute, in force from 2020, with a negative list that is revised and not printed here. Cybersecurity, data, and personal-information rules are a second regime. Content businesses carry political supervision that a factory-tooling firm may not feel in the same way.
The domestic market is large enough that a company can scale without exporting. That is the fact. No output figure is quoted. Export, when it is the plan, meets foreign investment screening and export controls on the other side.
Ports, airports, and the supplier base of the Pearl River Delta are physical connectivity. Data leaving the country, and a foreign shareholder arriving, are legal connectivity. They fail independently of the airport.
Power, freight, and high-speed rail are the base manufacturers assume. Digital infrastructure is extensive and supervised. Both belong in the location decision.
The constraints that bind a cross-border reader are the negative list, data export, capital controls, and the political boundary around content and education products. The constraint that binds a domestic hardware firm is qualification with customers and, for some components, foreign export control.
Manufacturing depth and the size of the home market are structural. The terms on which foreign capital can hold a company are political and can tighten or ease without a change in the engineering. Long-term potential is that split. It is not a growth rate.
Private firms are a normal part of the economy and are not outside politics. Founders in consumer internet learned, in public, that scale does not outrank the regulator. Industrial and enterprise software live under a quieter set of constraints and a closer relationship to factories and local government.
The ordinary vehicle is a limited company under Chinese company law. A foreign investor uses that law plus the foreign-investment regime. Variable-interest arrangements, the contractual structures associated with some overseas listings, are a market practice with regulatory risk. They are not ownership of the operating company, and this note does not restate the statute.
Domestic venture capital, local-government guidance funds, and corporate investors are part of the system. Foreign funds meet the negative list, foreign-exchange administration, and whatever outbound rules their own home regulator adds. A term sheet signed abroad does not close those files.
The technical base runs from consumer software to manufacturing equipment, batteries, and telecommunications hardware. Shenzhen’s supplier markets are a physical fact. Beijing’s advantage is research institutions and headquarters. Treating the country as a software story misses where the engineering of objects actually happens.
The labour market is national and city-specific at once. Hukou and housing policy still shape who stays. Returnees matter in some sectors and are not a strategy. Salary competition from large platforms and from state-linked industry is the outside option.
Tsinghua and Peking universities in Beijing, Zhejiang University, Shanghai Jiao Tong, and Fudan are research institutions with very large graduate output. A paper is not a company. Local governments run parks next to campuses precisely because the conversion does not happen by itself.
Foreign investment is the negative-list system described above. Data is a second regime: cybersecurity, data-security, and personal-information rules restrict what can be collected and what can leave the country. Content businesses carry a third, political, constraint. A fintech, a factory-software firm, and a media app are not under one risk.
Cost is city rent, social insurance, and the compliance staff a data-heavy product now requires. The discontinued Doing Business ranks are not used. A local accountant’s current schedule of contributions will beat any country essay.
High-speed rail, ports, power, and dense urban transit are the base the manufacturing startups assume. Digital infrastructure is extensive and monitored. Both facts belong in the same paragraph. Logistics inside China is not the constraint it is in an archipelago. Crossing the border with data or with a controlled technology is.
The domestic market can scale a company that never exports. That is the structural difference from a small-country startup scene. Export, when it happens, now meets investment screening and export controls on the other side, especially in the United States and Europe. Access to the Chinese customer and access to a foreign cap table are different problems.
Process and manufacturing innovation are as important as software. Public labs and state industrial policy are part of the innovation system, not a distortion sitting outside it. Copying a foreign consumer product into China is still a business. It is a weaker description of the hardware economy than it was of an earlier internet wave.
Scale inside the country is a distribution and compliance problem. Scale across the border is a geopolitical problem: which components are controlled, which investors are allowed to hold the equity, and which app stores and payment rails remain open. GRIP does not pick sectors that will clear those filters.
Across GRIP
The same place, read from another desk.
Continue with GRIP
Country briefs are the law and the national system. City briefs are where hiring, customers and rent actually happen.